By Kara Kay & Associates
Whether you want to open up a cramped beach-cottage kitchen or turn a side yard into an outdoor living room, the way you pay for a renovation shapes the entire project. The right choice depends on your equity, your timeline, and how much payment fluctuation you can live with. We want Pacific Beach homeowners and buyers to see every option side by side, so here's how to finance a home renovation with confidence.
Key Takeaways
- A clear scope and written bids come before any loan.
- Home equity options each fit different project styles.
- Renovation loans can fund repairs when equity is limited.
- Coastal permits affect timing and carrying costs.
Define the Project Before Choosing the Loan
The loan amount should follow the plan, not the other way around. A bathroom refresh in a cottage near Crystal Pier and a full remodel on a hillside lot near Kate Sessions Park are completely different financial commitments. Written contractor bids turn a rough idea into a number a lender can work with. They also reveal which pieces of the project matter most if the budget needs trimming.
Line Items That Belong in Every Budget
- Construction bids: Labor and materials based on written, itemized estimates.
- Design and engineering: Architect, designer, or structural engineer fees for larger changes.
- Permits and reviews: City of San Diego fees, plus coastal review when required.
- Contingency reserve: Extra funds for problems that only surface once work begins.
Using the Equity You've Built
For many owners, equity is the most affordable source of renovation money. How you tap it matters, because each structure behaves differently over time. Your current mortgage rate is a key factor. Owners holding a low rate often prefer to borrow alongside that loan rather than replace it.
Equity Options Compared
- Home equity line of credit: Draw funds as needed and pay interest only on what you use, usually at a variable rate.
- Home equity loan: A fixed lump sum with steady payments, well suited to a fixed-price contract.
- Cash-out refinance: Replaces your existing mortgage with a larger one, which can mean giving up your current rate.
- Matching the tool: A credit line suits phased projects, while a lump sum suits work with one clear price.
Renovation Loans for Buyers and Owners With Less Equity
Some loans are built specifically around improvements. They can be especially useful when buying a home that needs work, since one loan covers both the purchase and the renovation. These programs base the loan on the home's expected value after improvements, which can open doors that standard financing can't.
Purpose-Built Renovation Loans
- FHA 203(k) standard: Designed for larger projects, including structural work, with a consultant overseeing the process.
- FHA 203(k) limited: A streamlined version for smaller, non-structural repairs and updates.
- Fannie Mae HomeStyle: A conventional option that covers a broad range of improvements.
- Draw schedules: Funds are released in stages as work is completed and verified.
Options for Smaller Projects
Not every update needs a mortgage product. A new front door, refinished floors, or an outdoor shower for rinsing off after the beach may be better handled with simpler tools. Shorter-term financing usually costs more in interest, so it works best when the balance can be paid down quickly.
Alternatives for Smaller Budgets
- Cash savings: No interest or approval process, though it reduces your reserves.
- Personal loans: Unsecured funds with fixed terms that don't involve your home as collateral.
- Promotional credit cards: Introductory rates can help if the balance is cleared before the promo ends.
- Contractor financing: Payment plans offered through some contractors, worth reading closely.
Coastal Timing and Carrying Costs in Pacific Beach
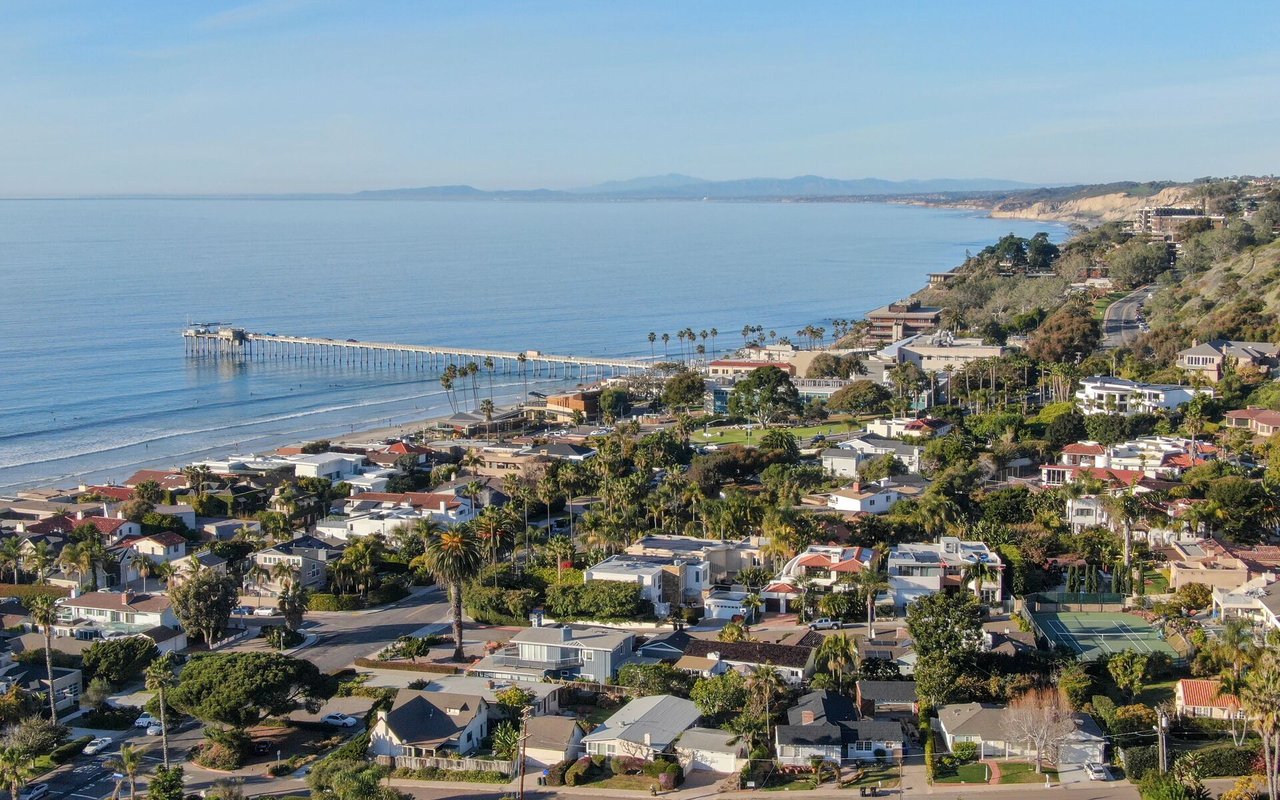
Much of Pacific Beach sits within San Diego's coastal zone, where some projects require a Coastal Development Permit. The 30-foot Coastal Height Limit also affects second-story and roof deck plans. Permit review can extend how long you hold a loan before work begins. Building that time into your plan keeps surprises off the balance sheet.
Timing Factors to Plan Around
- Permit review: Confirm requirements with the Development Services Department before locking in financing.
- Interest during waiting: A lump-sum loan starts accruing interest the day it funds.
- Draw periods: A credit line's draw window should comfortably cover the full project.
- Temporary housing: Factor in rent elsewhere if the home won't be livable during construction.
Comparing the True Cost of Each Option
Two loans for the same amount can cost very different sums over their lifetime. The interest rate is only one piece, and fees, terms, and rate structure all shape the final number. Asking lenders for written estimates lets you compare real figures for a Pacific Beach kitchen remodel or a new bayside patio instead of relying on advertised rates.
Numbers to Compare Side by Side
- Rate structure: Fixed rates stay steady, while variable rates can rise or fall over time.
- Upfront fees: Origination, appraisal, and closing costs change the true cost of borrowing.
- Repayment term: Longer terms lower the monthly payment but usually increase total interest.
- Prepayment flexibility: Check whether you can pay the balance down early without penalties.
FAQs
What's the best way to finance a renovation in Pacific Beach?
It depends on your equity, your current mortgage rate, and the size of the project. We recommend comparing at least two options with a lender, and we're happy to help you think through the plan.
Can I finance a renovation when I buy a home?
Yes, programs like FHA 203(k) and Fannie Mae HomeStyle can combine the purchase price and repair costs into one loan. Eligibility requirements apply.
Will a renovation increase my home's value?
Well-planned updates often improve appeal, but results vary by project and property. We can talk through which upgrades make sense for Pacific Beach homes.
Contact Kara Kay & Associates Today
A solid financing plan makes a renovation easier to start and easier to finish. At Kara Kay & Associates, we'd love to help you think through your options as a Pacific Beach homeowner or buyer.
Reach out to us at
Kara Kay & Associates to talk about your goals. Whether you're planning a kitchen refresh, a new outdoor living area, or a full remodel near the beach, we're ready to help you move forward with confidence.